The Great Data Center Mirage: Why the AI Infrastructure Boom Faces a Reckoning
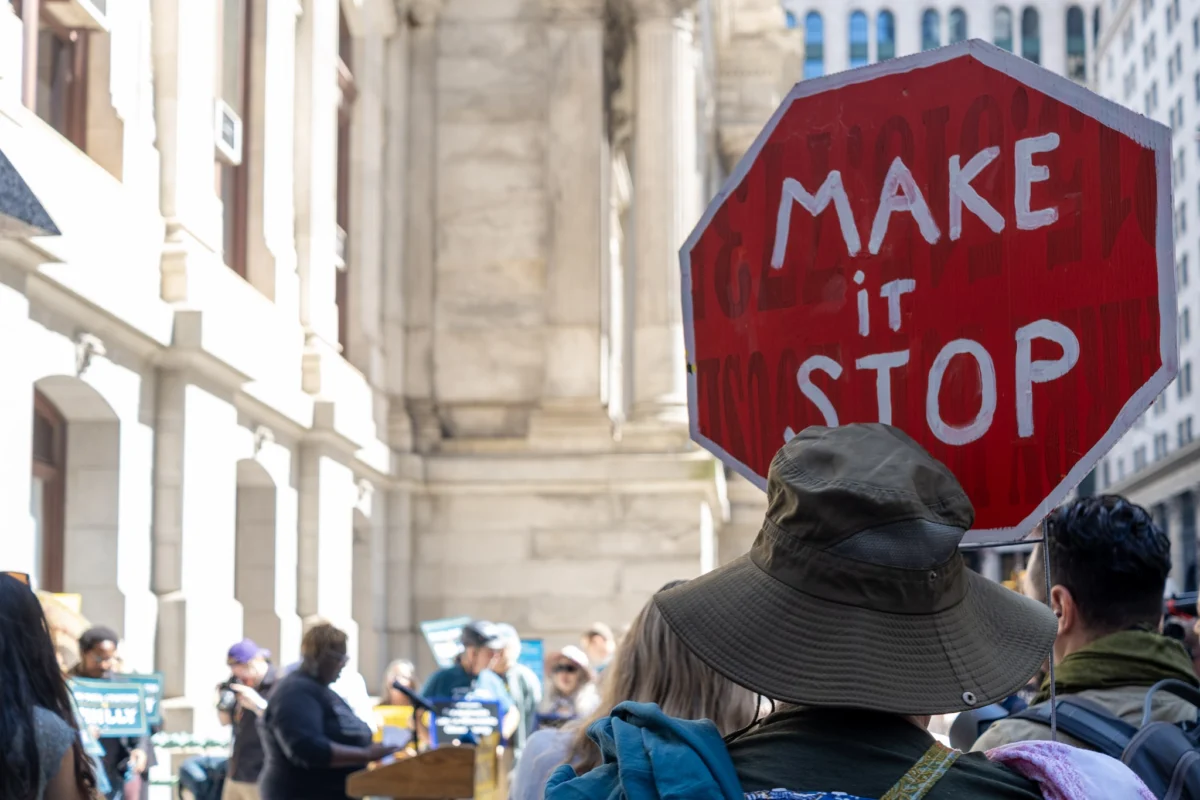
The global technology sector is currently gripped by an unprecedented "land grab" for digital infrastructure. Driven by the voracious appetite of generative artificial intelligence (AI) and large language models (LLMs), tech giants and private equity firms have announced hundreds of billions of dollars in new data center developments. However, a growing chorus of experts warns that the industry is hitting a physical wall. Between widespread local opposition, a crumbling power grid, and the sheer speculative nature of many "paper projects," the gap between announced capacity and actual operational reality is widening.
On a recent episode of TechCrunch’s Equity podcast, hosts Rebecca Bellan and Tim De Chant sat down with Brent Nelson, Senior Managing Director of Markets and Strategy at Ascend Analytics, to dissect this phenomenon. The consensus is sobering: while the demand for compute is real, the ability to deliver the physical structures to house it is increasingly compromised.
Main Facts: The Disconnect Between Capital and Capacity
The primary tension in the data center market today is the disconnect between financial commitment and physical feasibility. Microsoft, Google, Meta, and Amazon have collectively signaled hundreds of billions in capital expenditures (CAPEX) for AI infrastructure. Yet, as Brent Nelson points out, the industry is entering a phase where "separating realistic projects from speculative ones" is the most critical task for investors and policymakers alike.
The Rise of Speculative "Paper Projects"
A significant portion of currently announced data centers may never be built. In the industry, these are often referred to as "paper projects"—developments that have been announced to boost stock valuations or secure land rights but lack the necessary power interconnection agreements or local zoning approvals.
The Three Pillars of Obstruction
The "boom" is currently being throttled by three primary obstacles:
- Grid Saturation: The U.S. power grid, particularly in hubs like Northern Virginia and Texas, is reaching its limit. Data centers now require "gigawatt-scale" power, which the current infrastructure was never designed to handle.
- Permitting and Regulatory Friction: Local governments are moving from welcoming data centers with tax breaks to halting them with moratoriums.
- Community Backlash: Residents are increasingly vocal about the environmental and aesthetic costs of data centers, citing noise pollution from cooling fans and the massive consumption of local water supplies.
Chronology: From the Cloud Era to the AI Explosion
To understand the current bottleneck, one must look at the evolution of data center demand over the last decade.
2010–2020: The Linear Growth of the Cloud
During this decade, data center growth was largely driven by the transition from on-premise servers to the cloud (AWS, Azure, GCP). Growth was steady and predictable. Utilities could plan for new loads over five-to-ten-year horizons. Most data centers were "enterprise-scale," consuming between 10 and 50 megawatts (MW).
2021–2022: The Post-Pandemic Digital Surge
The COVID-19 pandemic accelerated digital transformation, increasing the demand for streaming, remote work, and e-commerce. This led to the first signs of strain in "Data Center Alley" (Loudoun County, Virginia), where Dominion Energy warned that power delivery might lag behind building construction.
2023: The Generative AI "Big Bang"
The release of ChatGPT and the subsequent AI arms race changed the metrics of the industry overnight. AI training requires exponentially more power than standard cloud storage. The industry shifted from requesting 50MW to requesting 500MW or even 1,000MW (1 Gigawatt) for a single campus.
2024–Present: The Physical Pushback
By mid-2024, the "real-world obstacles" mentioned in the Equity podcast became unavoidable. In August 2024, Texas Governor Greg Abbott called for audits of data centers, questioning their strain on the ERCOT grid. Simultaneously, the PJM Interconnection—the largest grid operator in the U.S.—began facing internal strife as AI demand threatened to drive up electricity prices for everyday consumers.
Supporting Data: The Magnitude of the Energy Crisis
The numbers underlying the data center boom illustrate why the current trajectory is unsustainable without radical intervention.
Power Demand Projections
According to the International Energy Agency (IEA), data centers’ electricity consumption could double by 2026. In the United States, data centers are projected to consume 6% of total electricity by 2028, up from roughly 2.5% in 2022. In specific regions like Virginia, data centers already account for over 20% of the total load.
The Interconnection Queue
The "interconnection queue"—the list of projects waiting to be plugged into the grid—has become a graveyard for speculative projects. In many regions, the wait time to get a high-voltage connection is now seven to ten years. Brent Nelson of Ascend Analytics highlights that many developers are "squatting" in these queues, holding onto spots for projects that lack financing, simply to flip the land or the permit to a larger player later.
Water Usage and Noise
A typical 100MW data center can consume upwards of 1.1 million gallons of water per day for cooling—roughly the same as a city of 10,000 people. As AI chips run hotter (Nvidia’s Blackwell chips require significantly more cooling than previous generations), the pressure on local water tables has become a primary point of contention in arid regions like Arizona and parts of Texas.
Official Responses: Regulators and Utilities Step In
As the friction between tech ambitions and infrastructure reality intensifies, government officials and utility providers are shifting their stances.
State-Level Interventions
In Texas, the state government has moved from a "hands-off" approach to active scrutiny. Governor Greg Abbott’s call for audits reflects a growing concern that data centers—specifically those involved in crypto mining and AI—provide relatively few jobs compared to the massive amount of subsidized electricity they consume.
In Maryland and Virginia, state legislators are debating bills that would require data centers to meet stricter "green" standards and provide more transparent reporting on their backup diesel generator emissions, which have become a major local health concern.
The Utility Perspective
Utility companies are in an impossible position. They are mandated to provide reliable power to residents but are being courted by tech companies willing to pay premiums for "front-of-the-line" access. The PJM Interconnection has seen heated debates regarding who should pay for the massive grid upgrades—the tech companies driving the demand or the general ratepayer. Currently, many grid operators are moving toward a "beneficiary pays" model, which could significantly increase the cost of building new AI hubs.
Tech Giants Turn to Nuclear
In response to the grid crisis, companies like Microsoft and Amazon are taking matters into their own hands. Microsoft recently signed a deal to resurrect a reactor at the Three Mile Island nuclear plant, while Amazon purchased a data center campus directly connected to a nuclear facility in Pennsylvania. This "behind-the-meter" strategy allows them to bypass the public grid and avoid some of the permitting delays associated with standard utility connections.
Implications: A "Great Winnowing" of the AI Sector
The constraints discussed on Equity suggest that the AI industry is headed for a period of consolidation and "de-risking."
The Survival of the "Hyperscalers"
The primary implication is that only the largest players—the "Hyperscalers" like Google, Amazon, and Microsoft—have the political and financial capital to navigate these obstacles. Small-to-mid-sized data center developers are likely to be squeezed out as the costs of power, water, and regulatory compliance skyrocket.
Geographic Decentralization
As traditional hubs like Virginia and Santa Clara reach capacity, developers are looking toward "frontier" markets. This includes regions with legacy industrial infrastructure, such as the Rust Belt, or areas with abundant but stranded renewable energy, like the Dakotas. However, moving to these regions often brings new challenges, such as a lack of fiber-optic connectivity and a dearth of skilled technical labor.
The AI Growth Ceiling
Perhaps the most significant implication is the potential for an "AI growth ceiling." If the physical infrastructure cannot keep pace with the software development, the deployment of AI could slow down. This would lead to a correction in the valuations of AI companies that have assumed infinite scalability.
Energy Innovation as a Requirement
The data center crisis is forcing a secondary boom in energy technology. From Small Modular Reactors (SMRs) to long-duration energy storage and liquid cooling systems, the survival of the AI sector is now inextricably linked to the decarbonization and modernization of the power grid.
Conclusion
The data center boom is not just a story of technological progress; it is a story of the limits of the physical world. As Brent Nelson and the Equity team noted, the "scramble for electricity" and "local opposition" are not just hurdles to be cleared—they are the new defining features of the landscape. For investors, the challenge is no longer finding a project to fund, but identifying which projects have a realistic path to being energized. As the "paper projects" fade away, only those that can harmonize their massive resource needs with local community and grid realities will remain standing in the AI era.